

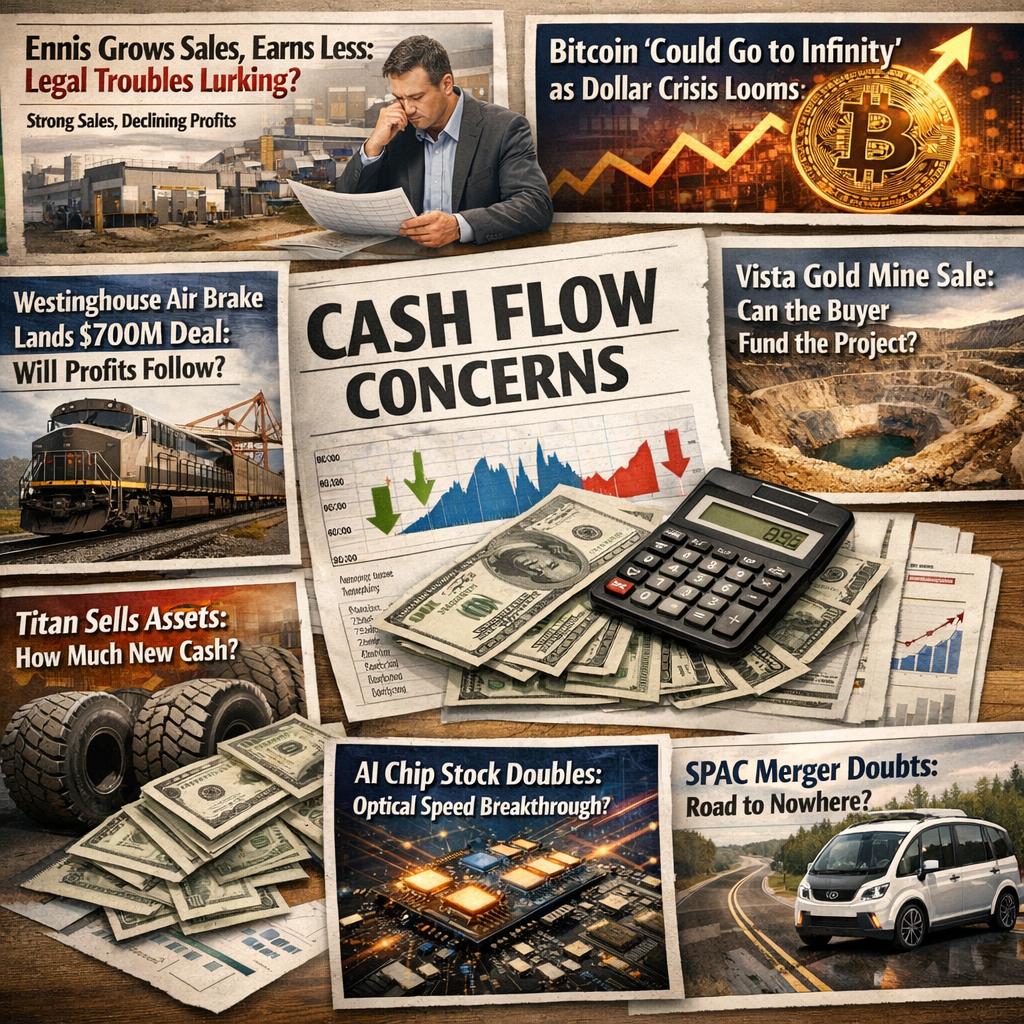
Amidst the usual market chatter about interest rates and AI’s boundless future, a quieter, more fundamental story often slips through the cracks: the simple, unglamorous reality of cash flow. It’s the lifeblood of any business, the metric that separates a thriving operation from a struggling one, regardless of what the headline earnings might suggest. A cluster of headlines from the market this week throws this into sharp relief, presenting a fascinating study in contrasts between sales growth and genuine financial health.
Take the case of Ennis. The report notes the company grew its sales, a headline that typically triggers a positive reaction. Yet, it simultaneously earned less. The immediate question posed—whether legal items are hiding a better business—is the right one. It points directly to the core principle that sales growth is not synonymous with profit growth or, more importantly, cash generation. A company can be moving more product than ever but if margins are compressed, costs are soaring, or one-time legal settlements are gutting the bottom line, that sales figure becomes a hollow victory. For investors, this is a critical reminder to look several layers down past the top-line revenue. The quality of earnings, the sustainability of margins, and the trajectory of free cash flow are what ultimately determine a stock’s long-term value. Ennis’s situation is a textbook example of why the income statement needs to be read in conjunction with the cash flow statement.
This theme of looking beyond the initial announcement extends to other stories. Westinghouse Air Brake signs a substantial $700 million-plus rail services deal, and the immediate query is about profit growth. It’s a prudent question. A massive contract is excellent news, but the market’s next move will be to model its profitability. What are the margins on this service work? Is it low-margin, high-volume maintenance, or more specialized, profitable consulting? The deal signifies demand and competitive strength, but the subsequent earnings calls will dissect its contribution to the bottom line.
Similarly, the Vista Gold sale agreement prompts a brilliantly operational question: can the buyer fund the Mt Todd Gold mine? A sale provides an exit and liquidity, but the true value of the underlying asset—the gold mine—is only realized if the new owner has the capital and expertise to bring it into production. The headline speaks to a corporate transaction; the subtext is all about execution risk and future cash flows under a different steward. It’s a shift from valuing a company as a standalone entity to valuing it as a project in the hands of another, which requires a completely different risk assessment.
Contrast this with the speculative fervor in other corners of the market. While analysts drill into the cash flow implications of a tire sale at Titan International or the viability of a SPAC merger for May Mobility, we have declarations that an asset like Bitcoin could “go to infinity” amid a dollar debt crisis. This is the polar opposite of a cash flow analysis. It’s a macro, almost philosophical bet on a systemic breakdown and the redefinition of what constitutes a store of value. One approach is grounded in dissecting the minutiae of corporate financials; the other is a wholesale bet against the existing financial system’s architecture. Both are valid in their own contexts, but they appeal to fundamentally different investor psychologies and risk tolerances.
What’s particularly interesting is how this plays out even within the hot theme of AI. The news about a little-known AI chip stock doubling on the back of a technical breakthrough in optical speed is a pure growth-and-innovation narrative. The market is pricing in future dominance and massive potential cash flows that are years away. Yet, simultaneously, we see notes about the AI optics trade potentially “splitting apart,” as evidenced by divergent moves between Lumentum and Corning. This suggests that even within a secular trend, the market is starting to discriminate, trying to identify which companies will actually capture the tangible, near-term cash flows from AI infrastructure build-out and which might be left behind.
For the global investor, the lesson here is about discipline. The market will always present both opportunities: deep-value situations where you must dig for hidden cash flow potential, and high-growth, high-conviction bets on a disruptive future. The key is to know which game you’re playing and to apply the appropriate analytical lens. Basing a long-term investment in a company like Ennis or Westinghouse Air Brake on a vague macro hope would be misguided, just as it would be to analyze a speculative tech bet solely on its current free cash flow yield.
These stories collectively underscore that while narratives drive short-term market sentiment, cash flows ultimately determine long-term value. The companies that can translate their sales, their deals, and their technologies into consistent, growing streams of cash will be the ones that endure, regardless of whether the broader narrative is about AI, infrastructure, or even a debt crisis. It’s a timeless principle playing out in real-time across these disparate headlines. I’d be keen to hear your take—are there other companies where you see a stark divergence between the headline story and the cash flow reality? Feel free to comment below.





