

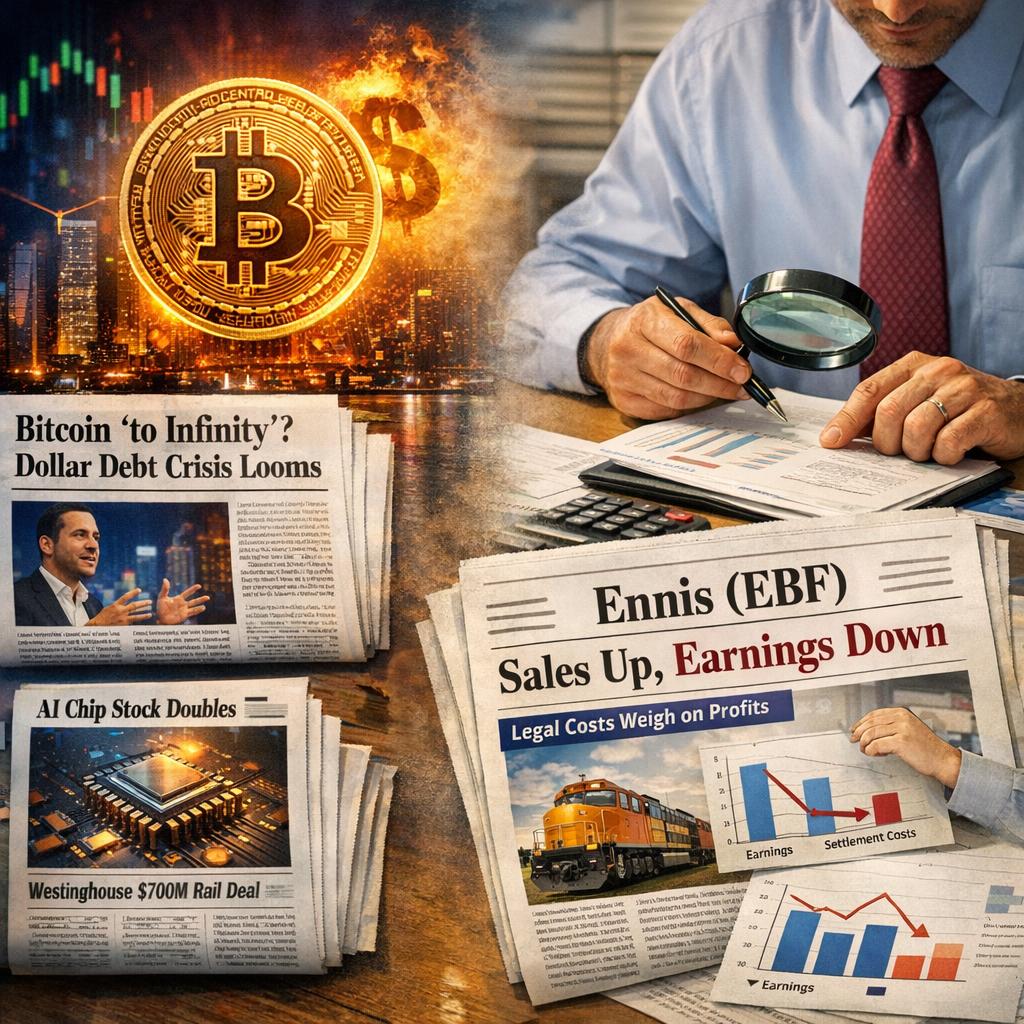
A scan of today’s market headlines reveals a fascinating dichotomy. On one side, the familiar, almost gravitational pull of transformative narratives: the relentless march of AI, the geopolitical chess game over semiconductor supremacy, the apocalyptic—or liberating—promises for Bitcoin. On the other, a quieter, more granular reality: companies signing contracts, selling divisions, reporting earnings that don’t quite add up at first glance.
One story from this latter category caught my eye, precisely because it serves as a masterclass in looking beyond the headline numbers. It concerns Ennis (EBF), a company that on the surface delivered a perplexing quarterly result: sales grew, but earnings fell. The immediate, instinctive reaction from many might be one of concern—growing the top line but losing profitability is rarely a sign of robust health. Yet, as the reporting suggests, the devil, and perhaps the opportunity, is in the details. A significant legal settlement charge appears to be the primary weight dragging down net income. This presents a critical question for any serious investor: are we looking at a deteriorating business, or simply a one-time cost obscuring an otherwise stable or even improving underlying operation?
This is where the real work of analysis begins, far removed from the speculative fervor of other market segments. Stripping out non-recurring items—legal settlements, asset sale gains, restructuring costs—is Finance 101, but it’s a discipline that is often forgotten in the rush to react to an earnings press release headline. The Ennis situation forces us to ask: what does the core business, the day-to-day generation of profits from its ongoing operations, actually look like once this unusual expense is set aside? If the adjusted earnings show resilience or growth concurrent with that sales increase, the narrative flips entirely. The market’s initial negative reaction could represent a mispricing, a temporary disconnect between reported results and economic reality.
This scenario is a potent reminder of a fundamental investment principle: not all earnings are created equal. Quality of earnings matters immensely. A dollar earned from recurring, high-margin operations is worth significantly more than a dollar salvaged from a one-time tax benefit or a non-core asset sale. The Ennis report, pending a deeper dive into their adjusted figures, challenges us to differentiate between a business facing structural headwinds and one that has simply weathered an isolated, albeit expensive, storm. It’s in this analytical trench work that long-term value is often uncovered, away from the glare of more hyped sectors.
This brings me to the contrasting noise from other parts of the market. While analysts pore over Ennis’s balance sheet, elsewhere, declarations are being made about Bitcoin’s potential to “go to infinity” amid a dollar debt crisis. The two narratives couldn’t be more different in texture. One is a forensic examination of concrete, if messy, financial data. The other is a grand, systemic bet on a paradigm shift in the very concept of money and value. Both have their place in a global portfolio discussion, but they operate on entirely different risk-reward spectra and require vastly different analytical frameworks.
Similarly, the flurry of activity in AI and semiconductors—SK Hynix eyeing Intel’s facilities, the challenge to Nvidia’s networking moat, the outperformance of certain optics plays—speaks to a market aggressively pricing in a future state. These are bets on exponential growth, technological disruption, and market share conquests. The Ennis story, and others like the Westinghouse Air Brake rail deal or the Vista Gold sale, are about the here and now: contract execution, asset valuations, and the clean-up of corporate balance sheets.
For the global investor, this dichotomy is the current playing field. Success requires the ability to hold two mindsets simultaneously: the visionary who can grasp transformative trends and the meticulous accountant who can dissect a GAAP income statement to find the true economic engine of a business. Ignoring the former means missing potential waves of growth. Ignoring the latter means risking overpayment for glamour or misunderstanding the fundamental health of a company.
The case of Ennis, should those legal items indeed be masking a better business, is a classic example of how market efficiency is sometimes more of an ideal than a constant reality. It is in the complexity, in the “noise” of one-time charges and special items, that gaps between price and intrinsic value can quietly open up. While the crowd chases the shiny object of a doubling AI chip stock or debates the merits of a SPAC merger for an autonomous vehicle company, the diligent work of recalibrating earnings models for an industrial name might yield a different, and perhaps more reliable, form of return.
It’s a useful exercise, on any given day, to separate the market’s stories into these two columns: the speculative future and the operational present. Both demand attention, but they demand different tools. Today, Ennis reminds us that sometimes the most insightful story isn’t the loudest one proclaiming a revolution, but the quieter one hiding in the footnotes of a financial statement. As always, I’m keen to hear your thoughts on where you’re finding clarity amidst the market’s mixed signals.





